Tilt: Cash Advance & Credit

- 99.35K Reviews
- 4.7
- Downloads
- 5,000,000+
 Analysis by Mobxio
When an expense lands just before payday, I want more than a quick way to borrow: I need to understand what I’m agreeing to, keep track of the rest of my budget, and avoid turning one tight week into a longer problem. Tilt: Cash Advance & Credit brings short-term cash options together with credit tools, score monitoring, saving, and budgeting. That breadth is useful, but it also means I’d treat the app as a financial workspace to review carefully—not as a substitute for having a plan to repay.
Starting with the problem, not the offer
I’d open Tilt with a specific question: is this expense urgent, and can I cover it from my next income without missing rent, bills, or another commitment? That small check matters because a cash advance can solve a timing gap without solving an income gap. If the numbers only work by borrowing again, I’d look first at rescheduling the bill, using savings, or asking the provider about a payment arrangement.
Tilt is a free finance app from Tilt Finance, and its mix of cash advances, credit lines and cards, score monitoring, savings, and budgeting gives users more than a single borrowing route. It has a 4.7 average from around 275,000 ratings and over 5 million installs. Those figures suggest a widely used app, but they don’t tell me whether a particular offer will suit my situation; I’d judge that by its actual terms and how clearly I can see the repayment impact.
From a cash gap to a workable plan
I’d begin by treating the cash gap as a timing problem to map, not an offer to accept automatically. In the section that follows, I’ll trace how I would move from checking the expense and my budget to weighing a borrowing option, paying attention to the handoffs and repayment details that can change the decision. A clear repayment plan is what turns convenience into something I can use responsibly.
Getting started with Tilt
Setting up Tilt: Cash Advance & Credit is as simple as pie. Just download the app, create an account, and you’re good to go. The interface is super intuitive, making it easy to navigate even if you’re not tech-savvy. Right from the get-go, it feels like the app was made with the user in mind, prioritizing ease of use and accessibility.
Before I choose any financial product, I’d slow down long enough to check what the app is asking me to do and what information I’m sharing. Then I’d compare the amount I need with the amount I can realistically repay, rather than treating an available limit as a recommendation. The useful outcome of that first pass is a clear decision: proceed only if the timing and repayment fit, or leave the borrowing option alone and use the budgeting tools to work through the shortfall.
Choosing a route and checking the handoff
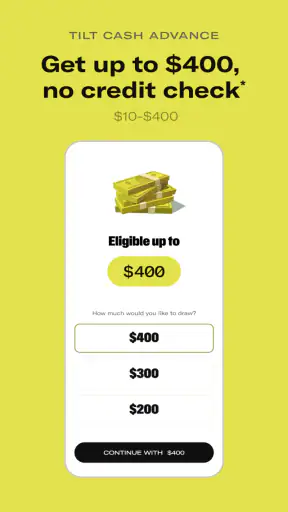
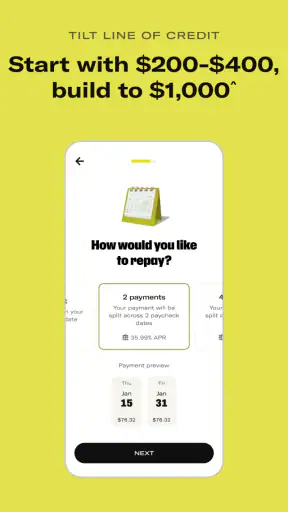
One of the things I love about Tilt is its cash advance feature. You can request advances up to a certain limit without any hidden fees. It’s like having a financial safety net, ready when you need it. Plus, the repayment terms are straightforward, so you won’t find yourself caught off guard by any sneaky charges.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
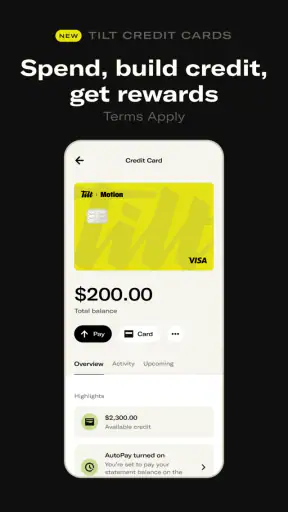
Because advances, credit lines, and cards are different ways of accessing money, I wouldn’t assume they carry identical costs or repayment rules. I’d read the terms shown for the specific option in front of me, check the due date and total obligation, and make sure I know what happens next before accepting. That is also where a handoff can matter: an app may help me review an option, but the actual movement of money and the repayment arrangement still need my attention. A convenient request button is not a reason to skip the details.
Putting the other tools to work
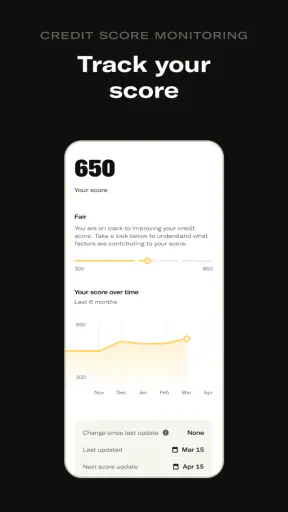
Another nifty feature is the credit building option. If you're looking to improve your credit score, Tilt offers tools and tips to help you along the way. It’s an all-in-one solution for managing your finances smartly.
I’d use the credit and score tools as prompts to build a repeatable routine, not as a promise that a score will change quickly. For example, I could check my score at a regular point in my month, then review my spending and upcoming obligations before taking on another credit commitment. Score monitoring is most useful when it leads to a practical next step; checking a number without changing a habit can feel reassuring without improving the underlying budget.
Budgeting and saving can also make the app useful on a week when I don’t need to borrow. I’d start by noting the next few essential expenses, then identify a small amount I can set aside without leaving myself short for bills. If an automatic savings option is available in my account, I’d keep the transfer modest until I know how it affects my cash flow. Automation can make saving easier, but it should never create an overdraft or force me back to credit to cover essentials.
A realistic payday-to-payday workflow
Imagine my paycheck is due soon, but a necessary expense arrives first. I’d use the budget view to check the bills already due, decide whether the gap is temporary, and compare the amount needed with what I can repay from the next pay cycle. If I consider an advance, I’d review its terms before requesting it, then note the repayment date alongside rent and other fixed costs. After the expense is handled, I’d revisit the budget and adjust a future saving target so the same timing problem is less likely to catch me off guard.
The important part of that workflow is the follow-through. I wouldn’t count money as available until I understand when it will arrive, and I wouldn’t treat an advance as extra income. If repayment leaves too little for necessities, I’d choose a different route if one is available, or contact the biller to ask about timing. Tilt can help organize the decision, but it cannot make an unaffordable repayment affordable.
Where Tilt fits—and where another option may be better
What really sets Tilt apart from other financial apps is its focus on transparency and user support. The app offers 24/7 customer service, which is a lifesaver if you ever run into any issues or have questions. Plus, the community forums are a great place to share experiences and tips with other users.
Against a basic budgeting app, Tilt’s appeal is that it places borrowing choices and money-management tools in the same setting. A standalone budget tracker may be better if I only want to categorize expenses and don’t want lending features in the mix. A bank’s own app may be the clearer place to manage an existing account or review transactions, while a nonprofit credit counselor can be a more appropriate starting point if debt is already difficult to manage. Tilt is most relevant when I want to examine short-term credit options alongside budgeting and score monitoring—not when I need a guaranteed solution to persistent financial strain.
For a user who has a short-lived cash-flow mismatch, understands the repayment plan, and wants to keep an eye on the wider budget, the combination can be practical. Someone who prefers never to borrow, is already juggling several repayments, or needs detailed financial planning may be better served by savings, a bank, or qualified advice instead. I’d also remember that access to a particular product depends on the offer and account details I see; the app’s range of tools doesn’t mean every option will be right for every person.
One useful habit is to make the decision away from the pressure of the moment. I’d write down the exact expense, the date it must be paid, and the amount I can spare on the repayment date before opening a borrowing offer. That simple checklist makes it easier to compare an advance with delaying a non-urgent purchase or asking a provider for more time. It also gives customer support a concrete question if I need clarification, instead of relying on a general impression that an option sounds affordable.
Another trade-off is attention. Having saving, budgeting, credit monitoring, and borrowing in one app may reduce the need to switch between tools, but it can also make it tempting to explore more products than I actually need. I’d keep my own goal in view: solve the current cash-flow issue, then use the budgeting side to reduce the odds of repeating it. I wouldn’t apply for a credit product simply because it appears beside a useful score or savings feature.
What to check before relying on it
The app is free to download, but I would not interpret that as meaning every financial product or transaction has no cost. Before accepting any offer, I’d inspect the terms presented for that specific product, including repayment timing and any charges. This is a sensible question to settle inside the offer flow rather than assuming the rules for an advance also apply to a credit line or card.
I’d also ask myself whether I need a cash product at all. If the problem is that I lose track of spending, budgeting may be the more useful starting point. If I’m trying to understand credit, monitoring and educational tools can support a routine, but they are not a substitute for reviewing my full credit picture or getting expert guidance when a decision is complex. And if I’m already relying on advances to cover ordinary expenses, I’d pause before borrowing again and focus on a sustainable plan.
Tilt is rated for Everyone, and it runs on Android 7.0 or later; the current version is 7.17.0.780. It was released on December 4, 2017, and its nearly 99,000 written reviews offer another broad signal of user experience. I’d still read recent feedback for practical context, while remembering that other people’s experiences cannot tell me the terms or eligibility I’ll see in my own account.
My take after tracing the whole process
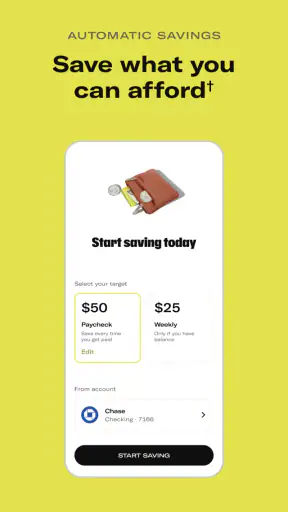
And let’s not forget the automatic savings feature. It’s like having a digital piggy bank that grows without you even noticing. This feature is perfect for those of us who struggle with saving money consistently.
In practice, I’d treat automatic saving as a tool to test gently: choose an amount that leaves room for necessities, then check whether it still works after bills and any repayment are accounted for. The benefit is a routine that can happen without repeated decisions; the risk is setting it too high and having to undo the transfer or borrow to compensate. That makes a small, sustainable contribution more valuable than an ambitious target that breaks the budget.
Final thoughts
In a world where financial stress is all too common, Tilt: Cash Advance & Credit offers a refreshing way to manage your money with less hassle. Whether you need a quick cash advance or are looking to build your credit, this app could be your go-to financial buddy.
So, if you’re on the lookout for an app that’s got your back when it comes to finances, give Tilt a whirl. It might just be the financial sidekick you didn’t know you needed.
Tilt: Cash Advance & Credit FAQ
What is Tilt: Cash Advance & Credit used for?
Tilt: Cash Advance & Credit is designed to provide users with quick access to cash advances and credit management tools. Ideal for those who need immediate financial assistance, it offers a user-friendly platform to manage short-term financial needs without the hassle of traditional bank processes.
How do I qualify for a cash advance with Tilt?
To qualify for a cash advance, users generally need to provide proof of stable income and meet specific credit criteria set by Tilt. The app may require linking your bank account for verification purposes, ensuring you have a reliable income stream to repay the advance.
Are there any fees associated with using Tilt?
Yes, using Tilt may involve fees, which can include service charges for cash advances or late payment penalties. It's crucial to review the app's terms and conditions to understand all potential costs. Transparent pricing is key, so always check the fee structure before proceeding.
Is Tilt secure for managing my financial information?
Tilt prioritizes user security by implementing advanced encryption and security protocols to protect your financial information. While no system is foolproof, regular updates and security audits help maintain a safe environment for managing your data.
Can Tilt affect my credit score?
Yes, using Tilt can impact your credit score. Timely repayment of cash advances may positively affect your credit, while missed payments can result in negative reporting. It’s important to manage your advances wisely and stay informed about how these financial activities influence your credit profile.
The Best Parts of Tilt: Cash Advance & Credit
Things to Keep in Mind About Tilt: Cash Advance & Credit